What is the Digital Chronic Disease Management Market overview?
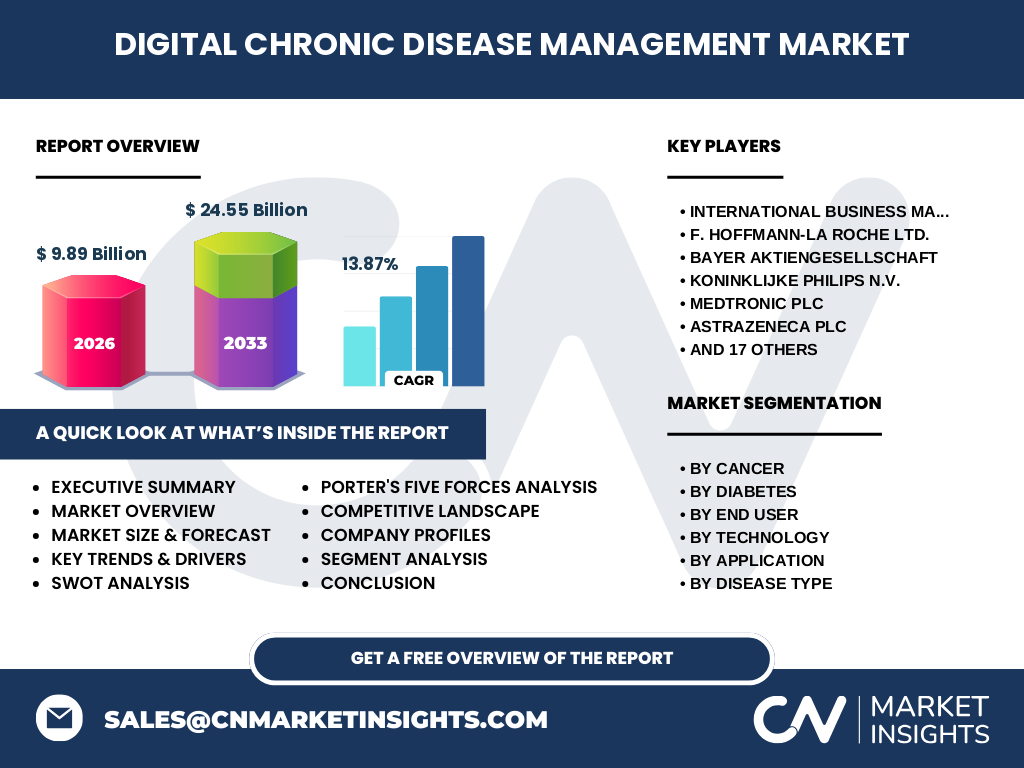
Our analysis indicates that the Digital Chronic Disease Management Market reached a valuation of 9.89 Billion in 2026. This sector encompasses advanced software and hardware solutions designed to monitor and treat long-term conditions like diabetes and cancer, significantly reducing hospital readmissions and improving patient outcomes globally.
Structural Growth Drivers and Restraints
The market is propelled by rising prevalence rates of obesity and cardiovascular diseases. However, stringent regulatory compliance required by bodies like the FDA and EMA acts as a primary market constraint, slowing down rapid product deployment and increasing compliance overhead for innovators.
Emerging Industry Trends in Digital Chronic Disease Management
The shift toward cloud-based and mobile application platforms is redefining care delivery. Industry leaders are increasingly integrating artificial intelligence for predictive analytics in remote patient monitoring, allowing for proactive interventions before acute clinical episodes occur.
How did the COVID-19 pandemic impact this sector?
The pandemic acted as a major catalyst, forcing healthcare providers to rapidly adopt telehealth services and mobile applications. This disruption permanently altered care delivery models, establishing a robust post-pandemic recovery trajectory centered on decentralized, home-based health management platforms.
Competitive Benchmarking and Market Concentration
The market features high competition among giants like Medtronic plc, F. Hoffmann-La Roche Ltd., and Teladoc Health Inc. Market concentration is moderate to high, with major players aggressively acquiring specialized digital health startups to expand their proprietary platform portfolios.
Executive Summary of the Digital Chronic Disease Management Market
Driven by rising patient demand for remote care, our research shows the Digital Chronic Disease Management Market is expanding rapidly. Strategic investments in wearable devices and cloud platforms will dictate long-term leadership across this healthcare ecosystem.
Market Forecast from 2027 to 2033
Projections show the market expanding from 2027 to 2033 to reach 24.55 Billion by the end of the forecast period. This robust growth represents a steady compound annual growth rate (CAGR) of 13.87%, fueled by widespread digital adoption.
Segmentation Analysis by Disease Type and Technology
The market segments by disease type include diabetes, cardiovascular diseases, and cancer, while technology divisions feature mobile applications, telehealth, and wearable devices. Each segment addresses specific clinical workflows, with diabetes management capturing significant revenue share due to high patient volumes.
Regional Market Analysis and Geographic Distribution
North America dominates the geographic distribution, supported by advanced healthcare infrastructure and high reimbursement rates for digital therapeutics. Meanwhile, Asia-Pacific represents the fastest-growing regional market due to expanding smartphone penetration and rising chronic disease burdens.
In-Depth Regional Review of Healthcare Infrastructure
Localized market constraints in Europe, driven by strict GDPR data privacy regulations, shape how cloud-based health platforms deploy. Conversely, the United States market prioritizes interoperability standards set by ONC, favoring scalable web-based and mobile solutions.
Strategic Positioning of Leading Company Profiles
Companies like DexCom Inc. and Abbott Laboratories focus heavily on continuous glucose monitoring hardware tied to mobile apps. Meanwhile, Omada Health Inc. and Virta Health Corp. specialize in behavioral lifestyle and metabolic disorder management platforms.
Porter's Five Forces Analysis
Competitive rivalry is intense due to numerous tech entrants, while the bargaining power of buyers remains moderate as hospitals demand proven clinical efficacy. Threat of substitution is low given the specialized nature of chronic disease software platforms.
SWOT Analysis of the Industry
Key strengths include scalable cloud deployments and high patient engagement. However, data security vulnerabilities represent a notable weakness. Opportunities lie in emerging market expansion, while threats stem from evolving data localization laws.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from semiconductor raw materials for wearable sensors to software developers creating health management platforms. Payors, healthcare providers, and patients sit at the end-user terminus, capturing clinical and financial value from reduced acute care costs.
Investment Insights and High-Potential Areas
High-potential investment areas include remote patient monitoring for heart failure and AI-driven predictive tools for diabetes management. Venture capital continues to favor interoperable platforms that easily integrate into existing Electronic Health Record systems.
Conclusion and Key Takeaways
The Digital Chronic Disease Management Market offers immense potential for stakeholders investing in scalable, secure technology solutions. Navigating regulatory hurdles will remain paramount for capturing long-term market share through 2033.
Research Methodology and Data Triangulation
Our baseline estimates are triangulated by combining trade registry data, primary stakeholder interviews with clinical leaders, and secondary macroeconomic indicators. This rigorous approach ensures accurate sizing of both hardware and software revenue streams.
Scope of the Report and Coverage Parameters
This report covers global deployment modes including cloud-based, web-based, and on-premise architectures across diverse end-users like payors and pharmaceutical companies. Limitations exclude non-digital traditional therapies and purely elective wellness products.
Recent Developments in Strategic Partnerships and Product Launches
Recent industry momentum is defined by strategic partnerships between tech innovators and pharmaceutical giants, alongside FDA clearances for advanced cardiac monitoring algorithms. Companies like Biofourmis and Glooko Inc. continue to announce major health system integrations.